SBC Summit Europe | 19-21 April 2027 | RAI Amsterdam
Table of Contents
There was a time when an online gambling operator could establish itself in one of Europe’s major licensing jurisdictions and use that base to build a business across multiple markets, where local law allowed.
Today, the landscape looks very different.
European countries have increasingly introduced their own licensing systems, bringing operators directly under the oversight of national regulators.
In 2009, just seven of the 31 European markets analysed by the European Gaming and Betting Association (EGBA) operated multi-licensing systems for online gambling. By 2024, that figure had risen to 27.
That shift has brought far more gambling activity under local regulatory frameworks. It has also left operators active across Europe holding several licences at once, each tied to its own regulatory requirements, which can include different approaches to taxation, advertising, technology, player protection and compliance.
It is a far cry from the earlier days of iGaming, when licences issued by jurisdictions such as Malta formed the basis of a more cross-border operating model. The Malta Gaming Authority (MGA) even described its licence as a point-of-supply licence, under which operators can provide services on a cross-border basis where they have a justifiable legal basis to do so.
At the same time, gambling regulation has never been fully harmonised at EU level. Member states retain significant autonomy over how gambling is regulated within their borders, and EU law does not require the mutual recognition of gambling licences issued by other member states.
In this blog, we examine what that increasingly fragmented regulatory reality means for operators today, and whether greater alignment across Europe is realistic, or even desirable.
One Continent, Multiple Licences
There is no single European gambling licence. In fact, there is no sector-specific EU legislation governing gambling services, with individual countries free to organise their own markets provided they comply with wider EU law.
That makes licensing one of the most obvious manifestations of fragmentation.
An operator based in Malta, for example, cannot rely solely on its MGA licence to serve British customers. The Gambling Commission explicitly requires overseas businesses to obtain a British licence if their gambling services are available to consumers in England, Scotland or Wales.
Multiply that across a European footprint and each new market can mean another application process, another regulatory relationship and another set of conditions that have to be maintained.
The licensing itself is therefore only the beginning.
Tax Can Change the Economics of a Market
Once licensed, operators also encounter very different approaches to taxation depending on the jurisdiction they are operating in.
The differences between some of Europe’s major regulated markets are substantial. In Sweden, licensed gambling is subject to a 22% tax ON gambling proceeds, calculated as the difference between stakes and payouts.
Italy sits slightly higher for certain forms of online gambling. From January 2025, online casino-style games, poker, bingo and other qualifying remote games are subject to a 25.5% tax on sums not returned to players as winnings.
Further north, the tax burden is considerably higher. The Netherlands increased its gambling tax from 30.5% to 34.2% in 2025 and then to 37.8% in 2026. Great Britain has gone further still for remote gaming, increasing Remote Gaming Duty from 21% to 40% from April 2026.
Those differences can materially change the economics of operating in a market. Put simply, for every €100 of GGR generated by an online casino, a 22% tax would leave €78 before the operator’s other costs, while a 40% tax would leave €60.
The Netherlands provides a recent example of what can happen as the burden rises. After the tax rate increased from 30.5% to 34.2% in January 2025, the Dutch Gambling Authority found that the increase had not delivered the intended rise in government revenue. GGR fell across both the online and land-based markets and, despite the higher rate, gambling tax receipts declined. The regulator stressed that several developments were affecting the market, rather than attributing the fall to taxation alone.
For operators deciding where to invest, taxation therefore becomes a fundamental part of a market’s attractiveness. A large customer base does not necessarily translate into an equally attractive commercial opportunity once the local tax burden is taken into account.
The Same Advertising Campaign Can’t Be Used Across Markets
Advertising rules provide one of the clearest examples of how differently European countries regulate the same industry.
Italy sits at the restrictive end of the spectrum. Under its 2018 Dignity Decree, the country introduced a broad ban on gambling and betting advertising, covering television, radio, print, billboards, digital channels and social media, as well as gambling sponsorship.
The Netherlands permits some advertising, but under tight restrictions. Online campaigns must reach an audience that is at least 95% aged 24 or over, operators cannot use role models such as influencers or professional athletes, and gambling sponsorship has been prohibited since July 2025.
Germany takes another approach. Advertising for virtual slots, online poker and online casino games is prohibited on television, radio and the internet between 6 am and 9 pm. Active athletes and sports officials cannot be used to advertise sports betting, while operators cannot advertise bets on a live sporting event immediately before or during its broadcast.
Britain is comparatively more permissive. Gambling advertising remains legal across a range of channels, but operators must comply with the UK advertising codes. Among other restrictions, gambling adverts cannot be likely to have strong appeal to under-18s, a rule that can prevent operators from using high-profile current footballers and other personalities particularly popular with younger audiences.
France also allows licensed operators to advertise, but restricts content that could encourage excessive gambling or appeal particularly to minors. Operators must also submit their promotional strategies to the ANJ for review each year, giving the regulator oversight of their planned advertising spend and activity.
The contrast is considerable. A campaign that is permissible in Britain or France could require significant changes in Germany or the Netherlands and may not be permitted at all in Italy.
For operators working across several European markets, there is therefore no single advertising strategy to roll out across the continent. Media plans, sponsorships, creative assets and brand partnerships all have to be assessed against the rules of the individual market, significantly increasing operating costs when operating across several jurisdictions.
Player Protection Can Reshape the Customer Journey
Player protection provides another example of different countries pursuing similar objectives through very different systems.
Germany operates a standard €1,000 monthly cross-provider deposit limit, enforced through its central LUGAS regulatory system. Virtual slots are also subject to a standard €1 maximum stake per game, although since July 2026 operators can permit higher stakes, up to €5, under additional conditions and player-protection requirements.
Operators have to connect to the LUGAS central files, which are used to monitor cross-provider deposit limits and prevent customers from gambling simultaneously with multiple operators.
Great Britain follows a different model. Remote operators are required to monitor customer behaviour and conduct financial vulnerability checks when a customer’s deposits minus withdrawals exceed £150 within a rolling 30-day period.
Both systems are intended to protect players, but the operational requirements are different.
For an operator active in both markets, safer gambling cannot simply be governed by one set of processes. Account controls, monitoring systems and customer interactions have to reflect the rules of the individual jurisdiction.
Not Every Product Can Be Offered
Sometimes the difference between markets goes beyond how a product is advertised or monitored.
It can determine whether the exact same game can be offered at all.
Take a typical online slot available in several regulated European casino markets. That same game cannot legally be offered through a licensed operator in France, where online casino games, including slots, fall outside the regulated online market.
Even where slots are permitted, the product may not be able to operate in exactly the same way.
Germany, for example, imposes market-specific requirements on virtual slots, including (until recently) a standard €1 maximum stake per game and an average minimum game duration of five seconds. Since July 2026, higher stakes of up to €5 can be permitted under additional conditions.
Denmark takes a different approach, allowing licensed operators to offer online casino products including gaming machines, roulette, blackjack, baccarat and poker.
For an operator or supplier, that means the same game could form part of a casino catalogue in one market, be unavailable altogether in another and require a different configuration before it can be launched somewhere else.
Multiply that across hundreds or thousands of games and several regulated markets, and maintaining a single European product catalogue becomes increasingly difficult, or well, impossible. Operators have to determine not only whether they can enter a jurisdiction, but which individual games they can offer there and what changes may be required before they go live.
Is Greater Alignment Realistic?
None of this makes national regulation undesirable. Countries have different policy priorities and retain autonomy over how gambling is organised, including which products they allow, how they tax the industry and how they protect consumers.
The question is whether every regulatory objective needs to be implemented differently.
There are already examples of a middle ground. The European Commission supported EN 17531, a voluntary European standard establishing common core elements for regulatory reporting while leaving the powers of national regulators intact. It also supports cooperation between national gambling regulatory authorities.
That may offer a more realistic direction than a single European regulator.
France does not have to legalise online casino because Denmark does, and Germany does not have to adopt Britain’s player-protection model. But where regulators are trying to achieve similar outcomes, there is a case for asking whether greater consistency around areas such as reporting, technical standards and compliance processes could reduce unnecessary duplication.
That conversation becomes increasingly important as operators, suppliers and affiliates build businesses across multiple European markets.
It is also one that will sit at the heart of SBC Summit Europe, bringing together regulators, operators, suppliers, affiliates, associations and policymakers from across the continent to compare approaches, understand where national markets genuinely need to differ and explore where greater alignment could benefit the wider industry.
Europe may remain a collection of separately regulated gambling markets. But bringing the people responsible for shaping and operating within those markets into the same room is an important step towards making that fragmentation easier to navigate.
Frequently asked questions (FAQs)
What is SBC Summit Europe?
SBC Summit Europe is the Home of European iGaming, with regulated markets at its heart. It is the annual meeting place for the people leading, regulating and building European gaming.
When and where does it take place?
19-21 April 2027 at RAI Amsterdam, the Netherlands.
Who will be there?
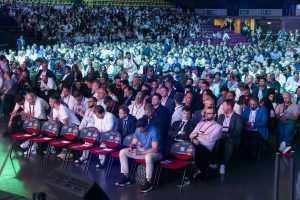
Around 8,000 attendees are expected, including more than 3,000 licensed operator representatives. They will be joined by regulators, policymakers, industry associations, legal experts, suppliers, affiliates, investors and media. SBC Summit Europe attendee overview.
What is the main focus of SBC Summit Europe?
SBC Summit Europe is where the people running, regulating and building licensed markets finally share a room. Regulators and policymakers join the conversation directly, alongside licensed operators, who sit at the heart of the event with more than 3,000 operator representatives expected. Networking is as much a priority as education, so the programme is built to turn insight into conversations, relationships and commercial outcomes that would be hard to arrange any other way. Partnerships with IAGR and IMGL, alongside relationships with regulatory bodies and industry associations, are bringing gaming authority representatives from across Europe to Amsterdam.
What topics will be covered?
Channelisation and black-market competition, taxation, advertising restrictions, player protection and affordability, licensing and compliance, and the impact of new technology and AI. The programme will also cover compliance technology, payments, sports betting platforms and data, casino, marketing and changing player behaviour. Check the SBC Summit conference agenda.
Is the event focused on one market or on Europe as a whole?
Both. Dedicated sessions explore individual jurisdictions in detail, while broader discussions look at the trends and lessons that apply across borders.
How can I get a pass?
Operators, regulators, and qualifying affiliates can apply for complimentary passes. For everyone else, registration will open soon. For now, register your interest for SBC Summit Europe.